

 Market
One sector, two playbooks: national concession model vs provincial fragmentation
André Moreira
Italy and South Africa show why gambling market expansion isn't just about demand, scale or digital maturity — it's about understanding the regulatory logic that actually determines who can enter, operate and win.
Most expansion conversations in gambling start in the same place: market size, mobile penetration, tax levels, product demand, competitive intensity.
That's understandable. It's also where many strategies begin to lose precision.
Because attractive fundamentals do not automatically translate into an accessible market. And in regulated sectors, the real differentiator is rarely demand alone. It is the structure around that demand: who controls access, how licences are granted, what level of fragmentation exists, and whether the operating model behind the business is truly compatible with the regulatory framework on the ground.
That's exactly why Italy and South Africa are such useful markets to analyse side by side.
Both are commercially relevant. Both have meaningful scale. Both deserve serious strategic attention. But they are governed by very different regulatory architectures and that changes everything.
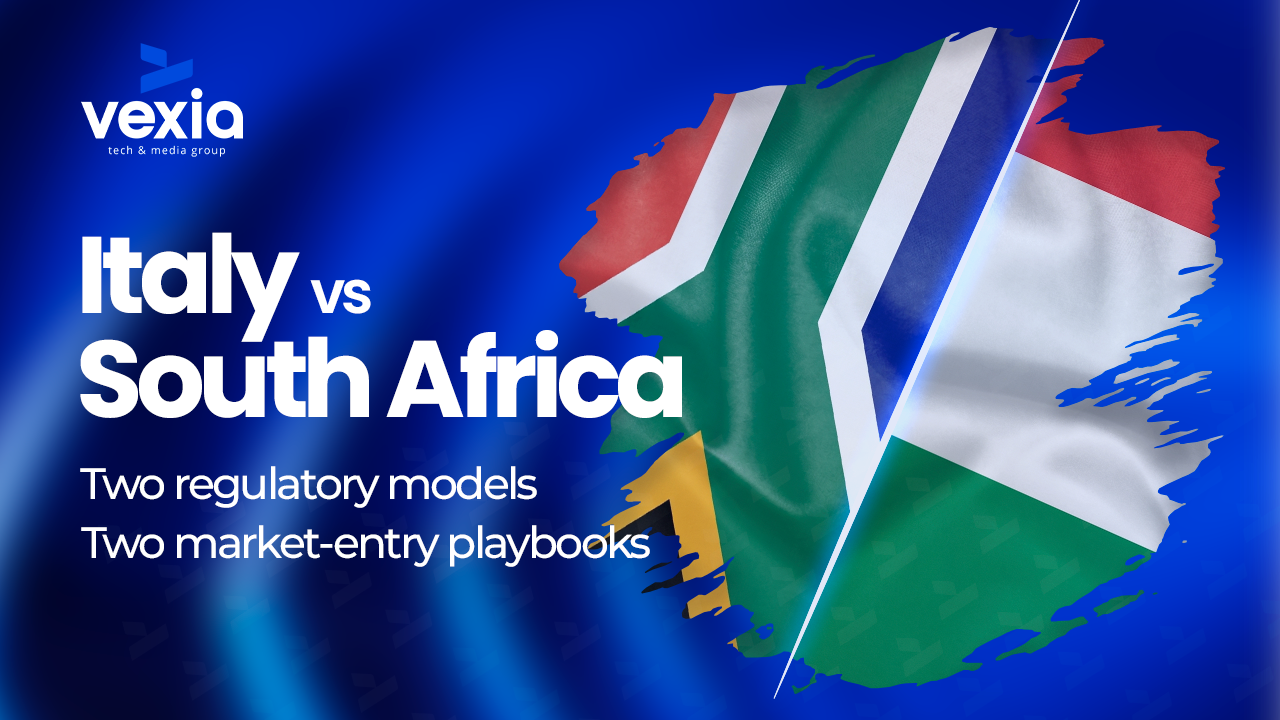
Italy reflects a tightly structured national concession model, with gambling overseen centrally by ADM and a clearly formalised framework for online operations. South Africa, by contrast, operates through a dual system in which national law sets the legal foundation, but provincial authorities license and supervise operators in practice. In simple terms: one market is shaped by centralised control, the other by regulated fragmentation.
That distinction is not just legal detail. It defines the commercial playbook.
The mistake many businesses still make
A common error in market expansion is to treat regulation as a compliance layer wrapped around a growth opportunity.
That's too simplistic.
In markets like Italy and South Africa, regulation does not sit around the business model. In many ways, it defines the business model. It determines which route to market is genuinely open, which capabilities matter most, how quickly scale can be achieved, and whether market entry is realistic or merely attractive in theory.
Two countries may both look investable at headline level and still require completely different execution disciplines.
That's the core lesson here.
Same sector, different execution logic
Italy and South Africa both belong in the broader conversation around regulated gambling growth. But they reward different capabilities.
Italy tends to favour scale, infrastructure readiness, capital strength and compliance discipline. It is a market where the rules are visible, centralised and demanding. If a business wants to enter, it must be ready to do so properly from the beginning.
South Africa tends to favour local intelligence, structural adaptability, licensing strategy and partnership capability. It is a market where opportunity exists, but the route to that opportunity is shaped by fragmentation and provincial variation rather than one national access model.
This is why generic discussions about “regulated market entry” often miss the point.
The real question isn't whether a market is regulated. The real question is what kind of regulation is organising the market and whether the business evaluating the opportunity is actually built for that model.
A company designed for centralised, infrastructure-heavy markets may struggle in fragmented multi-jurisdiction environments. A company that thrives through local partnerships and flexible market entry may still find itself underprepared for a high-cost, highly structured concession regime.
Same sector. Different playbooks.
What operators, investors and suppliers should take from this
For operators, the lesson is straightforward: don't confuse commercial attractiveness with market accessibility. Strong demand and digital momentum are important, but they are not enough. Entry assumptions need to be stress-tested against the real licensing architecture.
For investors, the point is just as important. Regulatory structure shapes not only market access, but also capital efficiency, timeline to scale, and the defensibility of business models already in-market.
For suppliers and B2B partners, these markets also show that value does not always sit in the same place. In some jurisdictions, the most realistic and scalable opportunity may be alongside the operator layer rather than at the consumer front end — something Italy illustrates particularly well.
The underlying principle is simple: market analysis becomes more useful when it moves beyond size and starts focusing on structure. Because structure is what determines who can actually execute. In regulated markets, opportunity is never just about where demand exists.It's about understanding what kind of market you are really entering and whether your business is prepared for the playbook that market demands.
Share Article